Thursday, June 22, 2017

Iron Condor Results Summary - Part 2 - Loss Levels

In the last article we looked at the backtest results from 600,912 iron condor trades entered between January 2007 and September 2016. The focus in that article was on win rate and normalized P&L per day for each of the 3024 variations tested.  Recall that we looked at combinations of:
  • Trade entry dates based on days to expiration (DTE)
  • Iron condor wing widths
  • Iron condor short strike position based on delta
  • Iron condor structures (standard balanced (ST), extra long put (EL), and delta neutral (DN))
  • Stop loss as a percentage of credit received (risk)
  • Profit target as a percentage of credit received (reward)

In this article we will look at a subset of those 3024 iron condor variations...the 2016 iron condor variations that used a profit target. Most traders don't want to carry their trades to expiration, but instead want to exit based on predefined profit targets and stop loss levels.

This article will look at several metrics in those 2016 iron condor variations, and group them by stop loss level. Many traders select strategies based on the amount of capital at risk, and a stop loss level can help define this amount. This article is meant to: a) help identify the optimal strategy variations based on stop loss level, and b) help identify the overall top performing strategy variations.


Stop Loss - 100% of credit received
  • 100% Stop Loss - Top 10 Strategy Variations By Metric
At this stop loss level, the trades entered at shorter DTE (specifically 38 DTE) dominate the top 10 average normalized P&L per day readings. This trend is visible even in the top 50 strategy variations at this stop loss level. The strongest combination to maximize P&L per day with a 100% stop loss level was 38 DTE, 25 point wings, 20 delta short strikes, standard structure (ST), with profit taking at 50%.
P&L Per Day - Top 10 Variations 

To maximize trade returns at this stop loss level, you'd look to initiate your trade between 73 and 80 DTE, with 25 point wings, with 20 delta short strikes, using the standard balanced IC structure (ST), with profit taking at between 50% and 75%.
P&L Per Trade - Top 10 Variations

Looking at the top 10 profit factors at this stop loss level sees another shift in the top performing strategy variations. The top profit factors were still associated with the 73 to 80 DTE starting range, but now we see the top variations having 50 point wings, with 8 delta short strikes, using the delta neutral (DN) IC structure, with profit taking leaning towards the 50% level.  The DN structure still dominates as we expand results to look at the top 25. It's also worth noticing that these combinations also have some of the highest Sortino ratios at this stop loss level.
Profit Factor - Top 10 Variations

The top 10 win rates at the 100% stop loss level were associated with strategy variations with short strikes at 8 delta and profit taking at 50%. These top variations also tended to have wing widths in the 50 to 75 point range, and also leaned toward delta neutral (DN) IC structures.  These top performing variations started anywhere from 59 to 80 DTE.
Win Rate - Top 10 Variations

  • 100% Stop Loss - Bottom 10 Strategy Variations By Metric
In contrast to the top 10 P&L per day strategy variations, the bottom 10 used the extra long put (EL) IC structure, with mid range starting DTE (45 - 59).
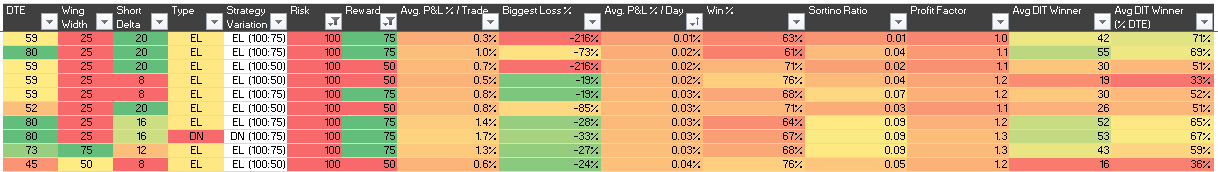
P&L Per Day - Bottom 10 Variations

The bottom 10 P&L per trade values were associated with mid range starting DTE (45 - 59), short strike deltas in the 8 - 12 range, and the extra long put (EL) IC structure.
P&L Per Trade - Bottom 10 Variations

The bottom 10 profit factors were also associated with strategy variations starting in the low to mid range DTE (38 - 66), with 25 point wings, 20 delta short strikes, and the extra long put (EL) IC structure.
Profit Factor - Bottom 10 Variations

At the 100% stop loss level, we see the bottom 10 strategy variations using 25 to 50 point wings, with 20 delta short strikes, using the extra long put (EL) IC structure, and taking profits at 75%.
Win Rate - Bottom 10 Variations

  • 100 % Stop Loss Summary
At the 100% stop loss level there were several strategy variations that work well, but these three stood out:
    1. 38 DTE, 25 pt. wings, 20 delta shorts, ST structure, 100% stop loss, 50% profit taking
    2. 80 DTE, 25 pt. wings, 20 delta shorts, ST structure, 100% stop loss, 50% profit taking
    3. 80 DTE, 50 pt. wings, 8 delta shorts, DN structure, 100% stop loss, 50% profit taking


Stop Loss - 200% of credit received
  • 200% Stop Loss - Top 10 Strategy Variations By Metric
As we move to the 200% stop loss level, the 38 DTE trades are no longer leading in the P&L per day metric.  The top 10 readings were dominated by trades initiated at 45 DTE, 25 point wings, 20 delta short strikes, using the standard balanced (ST) IC structure, with profit taking at 50%.
P&L Per Day - Top 10 Variations

The top 10 P&L per trade readings at this stop loss level were associated with strategy variations starting at 80 DTE, with 25 - 50 point wings, with 20 delta short strikes, using the standard balanced (ST) IC structure, with profit taking between 50% and 75%.
P&L Per Trade - Top 10 Variations

At this stop loss level, the top 10 profit factor readings were associated with strategy variations staring at 80 DTE, with 50 to 75 point wings, with 8 - 12 delta short strikes, and profit taking at 50%. There was not a clear pattern of IC structure out performance.
Profit Factor - Top 10 Variations

The top 10 win rates were dominated by trades starting at 80 DTE, 75 point wing widths, 8 delta short strikes, and profit taking at the 50% level.  The two top performing strategy structures were the extra long put (EL) structure, but following these top two positions, there was not a strong winner based on structure.
Win Rate - Top 10 Variations

  • 200% Stop Loss - Bottom 10 Strategy Variations By Metric
The bottom 10 P&L per day readings were again dominated by the extra long put (EL) structure with mid range DTE values of 52 to 66.  The wing width and short strike delta pattern present in the bottom ten variations did not continue when I looked at the bottom 50 performers. There was also no pattern present in profit taking level.
P&L Per Day - Bottom 10 Variations 

At the 200% stop loss level, the worst performing P&L per trade readings were associated with strategy variations starting between 38 and 59 DTE, with 8 delta short strikes, using the extra long put (EL) structure, and taking profits at 50%.
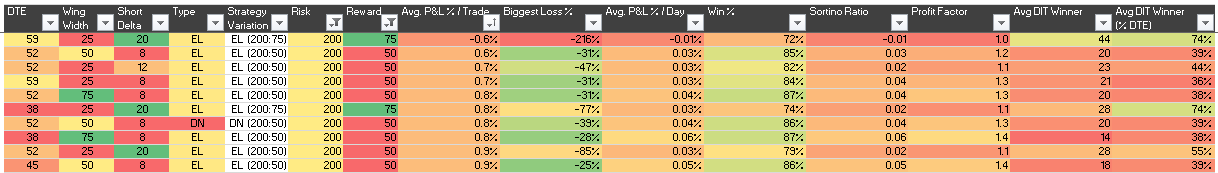
P&L Per Trade - Bottom 10 Variations

The lowest 10 profit factor values were associated with strategy variations starting between 38 and 59 DTE, with 25 point wings, with 20 delta short strikes, using the extra long put (EL) structure, and taking profits at 75%.
Profit Factor - Bottom 10 Variations

For the bottom 10 win rate values at the 200% stop loss level, we see the trend continue. The lowest readings are associated with strategy variations starting between 38 and 66 DTE, with 25 point wings, 20 delta short strikes, and profit taking at 75%.
Win Rate - Bottom 10 Variations

  • 200 % Stop Loss Summary
There were several decent strategies at the 200% stop loss level, but these stood out:
    1. 45 DTE, 25 pt. wings, 20 delta shorts, ST structure, 200% stop loss, 50% profit taking
    2. 80 DTE, 25 pt. wings, 20 delta shorts, ST structure, 200% stop loss, 50% profit taking
    3. 80 DTE, 75 pt. wings, 12 delta shorts, DN structure, 200% stop loss, 50% profit taking


Stop Loss - 300% of credit received
  • 300% Stop Loss - Top 10 Strategy Variations By Metric
At the 300% stop loss level, we see both shorter term and longer term variations appear in the top 10 P&L per day readings.  The top variations were 80 DTE, with 25 to 50 point wings (leaning towards 25 points!), 16 to 20 delta short strikes, using the standard balanced (ST) IC structure, with profit taking at 50%.
P&L Per Day - Top 10 Variations 

The top 10 P&L per trade readings were associated with variations initiated at 80 DTE, with 25 to 50 point wings, 16 to 20 delta short strikes, using the standard balanced (ST) IC structure, with profit taking at 75%.
P&L Per Trade - Top 10 Variations 

The top 10 profit factors were all associated with variations initiated at 80 DTE.  Wing widths tended toward the 50 to 75 point range, with deltas between 8 and 12, and profit taking at 50%.  There was no clear winner in terms of structure, with ST and DN having the strongest showing.
Profit Factor - Top 10 Variations

The top 10 win rates were also strongly associated with trades starting at 80 DTE.  Expanding the results to the top 30 highlighted that the top variations used 75 point wings, with short strike deltas between 8 and 12, and profit taking at 50%.  All structures were about equally present in the to 30.
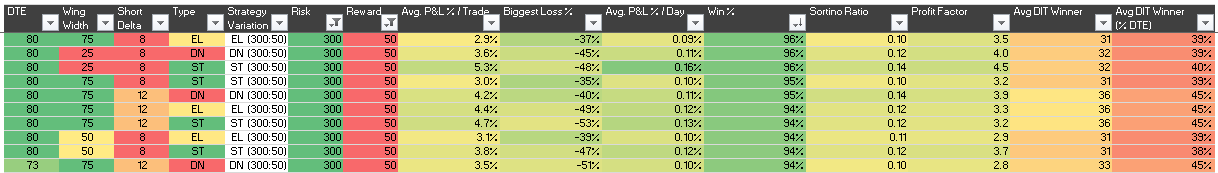
Win Rate - Top 10 Variations

  • 300% Stop Loss - Bottom 10 Strategy Variations By Metric
The worst 10 performing variations were associated with low to mid starting DTE (38 - 66), 25 point wings, 16 to 20 delta short strikes, with the extra long put (EL) IC structure. 
P&L Per Day - Bottom 10 Variations 

The worst 10 P&L per trade numbers were associated with variations starting between 38 and 52 DTE, with 25 point wings, 8 to 12 delta short strikes, the extra long put (EL) IC structure, and profit taking at 50%. This pattern was present in the bottom 30 variations.
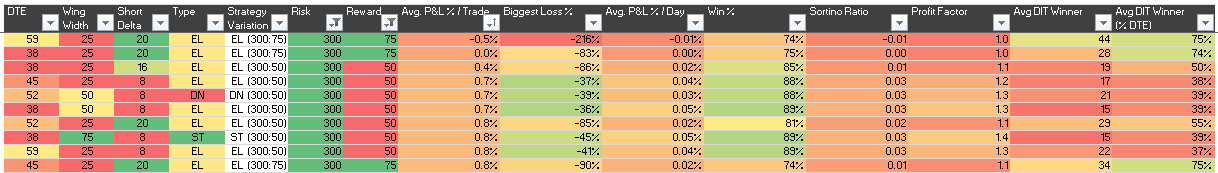
P&L Per Trade - Bottom 10 Variations 

The bottom 10 profit factor value were associated with low to mid starting DTE (38 - 66), 25 point wings, 20 delta short strikes, the extra long put (EL) IC structure, and profit taking at 50%.
Profit Factor - Bottom 10 Variations 

The worst 10 win rates were associated with low to mid DTE (38 - 66), 25 point wings, 20 delta short strikes, and profit taking at 75%.
Win Rate - Bottom 10 Variations

  • 300 % Stop Loss Summary
At the 300% stop loss level there were several strategy variations that work well, including:
    1. 80 DTE, 25 pt. wings, 8 delta shorts, ST structure, 300% stop loss, 50% profit taking
    2. 80 DTE, 50 pt. wings, 16 delta shorts, ST structure, 300% stop loss, 75% profit taking
    3. 80 DTE, 75 pt. wings, 12 delta shorts, DN structure, 300% stop loss, 50% profit taking


Stop Loss - NA - no stop loss
  • No Stop Loss - Top 10 Strategy Variations By Metric
For variations not using a stop loss, the top 10 P&L per day readings were associated with strategies starting at 80 DTE, with 25 point wings, 16 to 20 delta short strikes, using the standard balanced (ST) IC structure, and taking profits at 50%.
P&L Per Day - Top 10 Variations

The top 10 P&L per trade readings were associated with 80 DTE trades, using 25 to 50 point wings, 20 delta short strikes, with the standard balanced (ST) IC structure, and profit taking leaning toward 75%.
P&L Per Trade - Top 10 Variations

The top 10 profit factor readings were also associated with strategies starting at 80 DTE, with 8 delta short strikes, using the delta neutral (DN) IC structure, and profit taking at 50%.  The top 30 had all wing widths present in approximately equal numbers.
Profit Factor - Top 10 Variations

The top 10 win rates were associated with strategies starting at 80 DTE, using 75 point wings, with 8 delta short strikes, leaning towards the delta neutral (DN) IC structure, and profit taking at 50%.
Win Rate - Top 10 Variations

  • No Stop Loss - Bottom 10 Strategy Variations By Metric
The bottom 10 strategy variations in terms of P&L per day readings were associated with trades starting at 38 DTE, 25 point wings, using the extra long put (EL) IC structure.  There was no trend in short strike deltas and profit taking level.
P&L Per Day - Bottom 10 Variations

The bottom 10 P&L per trade readings were associated with trades starting at 38 DTE, 25 point wings, 8 to 12 delta short strikes, using the extra long put (EL) IC structure, and profit taking at 50%.
P&L Per Trade - Bottom 10 Variations

The worst 10 profit factors were also associated with trades starting in lower DTE range of 38 to 45 DTE, 25 point wing widths, and the extra long put (EL) IC structure. Short strike deltas were leaning towards the upper end of 16 to 20, and profit taking level was leaning towards 75%.
Profit Factor - Bottom 10 Variations

The lowest 10 win rates were associated with low to mid DTE levels of 38 to 52 DTE, 25 point wings, 20 delta short strikes, and the 75% profit taking level.  
Win Rate - Bottom 10 Variations

  • No Stop Loss Summary
The top performing strategies not using a stop loss included:
    1. 80 DTE, 25 pt. wings, 20 delta shorts, ST structure, no stop loss, 50% profit taking
    2. 80 DTE, 75 pt. wings, 8 delta shorts, DN structure, no stop loss, 50% profit taking


Summary

This was a fairly long article, but hopefully I've highlighted a strategy variation or two that you'd be comfortable trading...or modifying to suit your style. In the analysis above, it was clear that there were strategy variations at every stop loss level that were trade-able. Here are a few points that I noticed:

  • Normalized Average P&L Per Day
The top 10 P&L per day readings were about the same across the four different stop loss levels. As stop loss level increased, the required DTE also increased for these top P&L per day readings.  At the 100% stop loss level, there were a number of variations starting at 38 DTE, while at the 300% and no stop loss levels, the top variations tended towards 80 DTE.
At the lower stop loss levels, the best P&L per day numbers were associated with the 20 delta short strikes.  As the stop loss level increased, the top strategy variations started to include all of the different short strikes (8, 12, 16, and 20). 
Lastly, the best P&L per day numbers at the 100% stop loss level had the lowest win rates, but the smallest largest loss numbers.  As stop loss level increased, the win rate increased and the largest loss also increased.
  • Normalized Average P&L Per Trade
As stop loss level increased, the top P&L per trade readings also increased.  Win rates and profit factors also tended to increase with increasing P&L per trade readings.
Not surprisingly, the top P&L per trade readings were nearly all associated with strategies starting at 80 DTE, with 20 delta short strikes, using the standard balanced (ST) IC structure.
  • Profit Factor
As stop loss level increased, the top 10 profit factors also increased.  Win rate also increased with increasing profit factors.
  • Win Rate
As stop loss level increased, the top win rates also increased.  The top win rates were associated with strategies starting at 80 DTE, with 75 point wings, 8 delta short strikes, delta neutral (DN) IC structures, with profit taking at 50%.
The top win rates at the 100% stop loss level were lower (in the 80% range), but had some of the smallest largest loss numbers.  As win rate increased with stop loss level, largest loss numbers also increased (along with P&L per trade, P&L per day, and profit factor). 
  • Largest Loss
The smallest largest loss numbers tended to be associated with wing widths in the 50 to 75 point range, with 8 delta shorts.  The delta neutral (DN) structures had the smallest loss numbers at the low stop loss values, and the extra long put (EL) structures had the smallest loss numbers where no stop loss was used.
With no stop loss, the 80 DTE, 25 point wing, 8 delta short strike, EL, profit taking at 50% looks very interesting: largest loss is 62% of credit received, 99% win rate, 4.8% return per trade, and 30 DIT.
  • Sortino Ratio
Across stop loss levels, the highest Sortino Ratios were associated with trades starting at 80 DTE, 50 point wings, and profit taking at 75%.  At lower stop loss levels, the highest Sortinos were associated with 8 delta short strikes, with the 12 to 16 delta range dominating as stop loss level increased.

In the next article, I will look more deeply at the following strategy variations and how they are impacted by the three different IC structures:
    1. 38 DTE, 25 pt. wings, 20 delta shorts, 100% stop loss, 50% profit taking
    2. 80 DTE, 25 pt. wings, 20 delta shorts, 100% stop loss, 50% profit taking
    3. 80 DTE, 75 pt. wings, 12 delta shorts, 200% stop loss, 50% profit taking
    I may analyze one additional strategy in the next article based on reader comments...so let me know if there is a variation in addition to the three above that you'd like me to review!


    Follow my blog by email, RSS feed or Twitter (@DTRTrading).  All options are available on the top of the right hand navigation column under the headings "Subscribe To RSS Feed", "Follow By Email", and "Twitter". 

    Tuesday, May 9, 2017

    Iron Condor Results Summary

    Over the last several months I have shared the results from an extensive set of backtests of SPX iron condors (IC). In all, I backtested 600,912 individual SPX IC trades entered at varying days to expiration (DTE) between January 2007 and September 2016. The prior articles can be found at the links below:

    In this article, I'll review two key metrics collected from all of the backtests:
    1. Win Rate
    2. Normalized P&L Per Day

    Win rate is a common metric to analyze, but P&L per day is less obvious.  P&L per day gives us a very clear view of the expected return by day for a given strategy variation. We've already seen in the prior posts how the number of days in trade (DIT) increases as we enter trades at higher days to expiration (DTE). As a very rough rule of thumb, it takes about half the DTE to collect 50% of the credit (although this changes with short strike delta!). From this normalized P&L per day value we can derive the average return per trade, as well as the average return per year.

    Before we get into the results, I need to describe the format of the heat-map tables below. First, each IC wing width is presented in a separate table, starting with the 25 point wing ICs.

    Next, the first column lists the strategy variation, including the exit used. This column uses the strategy description nomenclature that I used in the last several months worth of articles in the links above.

    Next, there are four groups of seven columns. Each group corresponds to a different short strike delta, and each of the seven columns in the group corresponds to a different DTE starting point.


    Win Rate

    (click to enlarge)

    It's clear that the 8 delta short strike has the highest win rates from a delta perspective.  Also, 80 DTE has the highest win rate of all of the DTE tested.  The 50% profit taking level is the winner for profit taking exits. We also see that the larger wing widths have slightly higher win rates. Let's think about each of these points:
    • Both the smaller delta and higher DTE end up making a wider "tent" for the IC, which gives the market more room to run before a loss exit is triggered.
    • Taking profits at 50% versus 75% or expiration has you out of the trade sooner...reducing the chance that the market can move against your position.
    • The larger wing width, creates a larger credit, and at 75 points approximates a naked strangle. With 75 point wings, you get the margin relief (defined risk) from the long options that you don't get with a strangle. Since the longs are so far away from the short strikes, this structure has greater theta decay than ICs with 25 and 50 point wings.

    It's interesting to note that the win rate for the same short strike delta increases with increasing DTE. Recall, as DTE increases the implied volatility (IV) for the same delta option increases.  For example, an 8 delta put at 38 DTE might have an IV of 14.15% while an 8 delta put at 80 DTE might have an IV of 17.44%. Using these two examples of IV we calculate the expected one standard deviation move of the underlying in percent:
    • 0.1415  x  sqrt(38/365)  =  0.045656   (+/- 4.57%)
    • 0.1744  x  sqrt(80/365)  =  0.081648   (+/- 8.16%) 
    Note: IV from TOS for each of these option chains is lower at approximately 11.5% and 12.6% respectively

    Based on these expected moves, it's worth considering a couple of questions.  How does actual market movement over 40 days (half of 80 DTE) compare with the expected move?  How do the actual market moves over 19 days (half of 38 DTE) compare with those over 40 days?

    Finally, I have two tables showing the top 30 and bottom 30 IC variations in terms of win rate. The top variations are dominated by higher DTE, 75 point wings, 8 delta short strikes, profit taking at 50%, and no loss exit. The bottom 30 are dominated by mid-range DTEs, 25 point wings, 20 delta short strikes, extra long put (EL) structures, with loss taking at 100% and no profit taking exit (take the trade to expiration).

    (click to enlarge)


    P&L Per Day
    Recall from the prior articles that all of the P&L per day numbers are normalized. The P&L per day values shown in the charts below are expressed as a percentage of the max risk for that test run. Each of the different wing width ICs (25 point, 50 point, 75 point) will have a different max risk, and it is important to normalize daily returns by the associated max risk number. For example, a 25 point IC will have slightly less than $25K max risk (margin), while a 75 point IC will have slightly less than $75K max risk (margin). Since the 25 point IC will have approximately 1/3 the risk/margin, the $ returns need to be normalized by these varying max risk / margin numbers for proper strategy variation comparison.

    (click to enlarge)

    There are a few high level trends from these tables of normalized P&L % per day values:
    • The lowest returns occur with the EL structure.  The extra long put negatively impacts the theta decay of the structure, but this negative impact decreases (as we'd expect) as wing width increases
    • The next lowest returns occur with the DN structure. Since there are fewer call credit spreads than put credit spreads in this structure, there is lower theta decay than with the ST structure
    • The ST structure has the highest normalized P&L % per day numbers
    • From a short strike delta perspective, the lowest returns per day occur at 8 delta, and the highest returns occur in the 16 to 20 delta range
    • The 75 point wing structures have the lowest returns, and the 25 point wing structures have the highest returns
    • From a DTE perspective:
      • The DN structures' returns are highest in the 38 to 45 DTE range
      • The EL structures' returns are highest in the 73 to 80 DTE range
      • The ST structures' returns are highest in the 73 to 80 DTE range, but there is also a second high return clustering in the 38 to 45 DTE range

    The return distributions related to structure and DTE, suggest that in the 38 to 45 DTE range, the market has tended to trend up or stay flat.  Hence the clustering of higher daily return numbers for the DN structure in the 38 to 45 DTE range. Additionally, the data suggest that in the 73 to 80 DTE range the market has tended to stay flat or drop. The EL structure shows higher returns in longer duration trades, indicating that the extra long put has some benefit in the 73 to 80 DTE range. 

    Similar to the win rate section, I have two tables showing the top 30 and bottom 30 IC variations in terms of normalized P&L per day. The top variations are dominated by the standard (ST) structure with 25 point wings, 20 delta short strikes, profit taking at 50%, and a range of loss exits. The bottom 30 are dominated by the extra long put (EL) structure with 25 point wings, 20 delta short strikes, with no profit taking exit (take the trade to expiration).

    (click to enlarge)

    In the next article, we'll narrow down the list of 3024 strategy variations, to a list of strategies that look trade-able.  I'll remove the variations without profit and loss exits, and look at win rate, normalized P&L per day, largest loss, and profit factors.

    Also, over the next several days I'll use Twitter to share other versions of the tables above, organized around DTE groupings instead of grouping by short strike delta..


    Follow my blog by email, RSS feed or Twitter (@DTRTrading).  All options are available on the top of the right hand navigation column under the headings "Subscribe To RSS Feed", "Follow By Email", and "Twitter". 

    Saturday, April 29, 2017

    SPX Monthly Returns And Tail Risk

    I had some time yesterday while waiting for an appointment, and re-read "A Comparison of Tail Risk Protection Strategies in the U.S. Market".  One particular sentence in the paper caught my attention:
    "Remarkably, of the 24 months with greater than 5% loss in the S&P 500 between March 1990 and March 2011, 17 of them (or 71%) occurred with the S&P 500 below its 10-month moving average.7"
    The footnote associated with this sentence stated:
    "The ten-month or 200-day moving average is a popular technical indicator among market participants; its effectiveness in asset class timing is documented by Faber (2005)"
    I ran the same study in AmiBroker and Excel using the monthly closing prices of the SPX.  I calculated the 10 month moving average of SPX closing prices, and compared this value with the closing value of the first day of the next month.  For example, on March 1 1990, the closing price was 332.74, and the 10 month average of monthly closing prices was 338.59 (May 1989 through Feb 1990).  In this situation, March 1990 started below it's 10 month moving average.

    Looking at the same period of time as the Tail Risk Article (March 1990 - March 2011; 253 months), I found the following:
    • 70 of 253 months started below the 10 month moving average (28%)
    • 183 of 253 months started above the 10 month moving average (72%)
    • 25 of 253 months experienced a loss of 5% or more
      • 16 of these 25 months occurred when the month started below the 10 month moving average (64%)

    There were a few other points to note regarding winning and losing months:
    • 103 of 253 months were losing months (41%)
      • 36 of these 103 losing months occurred when the month started below the 10 month moving average (35%)
    • 150 of 253 months were winning months (59%)
      • 34 of these 150 winning months occurred when the month started below the 10 month moving average (23%)
      • 29 of these 150 winning months had monthly returns of greater than 5% (19%)
        • 14 of these 29 occurred when the month started below the 10 month moving average (48%)

    A few takeaways:
    • A greater percentage of the 5%+ monthly losses occurred when a month stated below the 10 month moving average
    • A month starting below the 10 month moving average is not a good indicator of whether the month will end with any loss ... the SPX has a positive bias
    • A month starting above the 10 month moving average is a good indicator of whether the month will end as a win (77%)
    • The numbers are similar when the range is expanded through March 2017


    Follow my blog by email, RSS feed or Twitter (@DTRTrading).  All options are available on the top of the right hand navigation column under the headings "Subscribe To RSS Feed", "Follow By Email", and "Twitter". 

    Wednesday, April 12, 2017

    80 DTE Iron Condor Results Summary

    This article reviews the backtest results for iron condors (IC) entered at 80 days to expiration (DTE). These tests covered 9 IC variations, with short strike deltas at four locations (8, 12, 16, 20), utilizing 12 exits.  In all, there were 432 test runs (9 variations x 4 deltas x 12 exits). Each test run executed an average of 165 SPX IC trades between the January 2007 expiration and the September 2016 expiration.  A total of 432 ten year backtests.  I used weekly options for this testing, so there were more than 12 trades per year.  In total, there were 71,388 total trades entered for the 80 DTE testing.

    You can find the prior SPX IC posts in this series at the links below:

    Normalized P&L per Day

    The P&L per day values shown in the charts below are expressed as a percentage of the max risk for that test run.  Each of the different wing width ICs (25 point, 50 point, 75 point) will have a different max risk, and it is important to normalize daily returns by the associated max risk number.  For example, a 25 point IC will have slightly less than $25K max risk (margin), while a 75 point IC will have slightly less than $75K max risk (margin).  Since the 25 point IC will have approximately 1/3 the risk/margin, the $ returns need to be normalized by these varying max risk / margin numbers for proper strategy variation comparison.

    The results:
    1. We continue to see more variability in P&L per day readings in the 25 point wing ICs, than in the larger wing width ICs
    2. Similar to the prior test runs, as the delta of the short strikes increases, the variability in the P&L per day readings increases
    3. The largest reading was 0.19%, which is the largest value we've seen in this series of IC tests.  There was one strategy variation with a 0.19% value:
      1. ST (NA:50), 25 point wings, 20 delta
    4. The next best readings came in at 0.18% and were associated with two test runs: 
      1. ST (NA:50), 25 point wings, 8 delta
      2. ST (200:50), 25 point wings, 20 delta
    5. 88 strategy variations had P&L per day readings of 0.12% or greater:
      1. Of these 88, 61 used the profit taking level of 50%
      2. Of these 88, 55 used the standard balanced (ST) IC structure
      3. Of these 88, 38 did not use a loss taking level (loss taking % = NA)
      4. Of these 88, 34 used wing widths of 50 points
      5. Of these 88, 32 used a short strike delta of 20 (30 used a delta of 16)
    (click to enlarge)


    Normalized P&L per Trade

    The normalized P&L per trade charts display returns expressed as a percentage of the max risk for a given test run.  As trade duration increases with increasing DTE, overall P&L per trade increases. Due to this fact, the max value of the y-axis on the 80 DTE P&L per trade charts was increased from 6% to 12% (similar to the 73 DTE P&L per trade charts).  At 80 DTE, all delta variations had some values exceeding the 6% level.

    The results:
    1. The variability in normalized P&L per trade again increases as the delta of the short strike increases, and decreases with increasing wing width
    2. In general, the returns per trade increase with increasing loss taking %, and this trend continues to be more pronounced as the trades move out in time / DTE
    3. The largest normalized P&L per trade was 9.4% and was associated with one strategy variation:
      1. ST (300:NA), 50 point wings, 16 delta
    4. 174 variations had P&L per trade values of 5.0% or greater...really large number!:
      1. 86 of these 174 were standard (ST) structures (45 were DN structures)
      2. 75 of these 174 did not use a loss taking exit (64 used the 300% level)
      3. 67 of these 174 did not use a profit taking level (59 used the 75% level)
      4. 66 of these 174 used a short strike delta of 20 (53 used 16 delta)
      5. 65 of these 174 used 50 point wings (58 used 75 point wings)
    5. The 80 DTE ICs have the largest average P&L per trade readings:
      1. 80 DTE: mean 4.60% / SD 1.98%
      2. 73 DTE: mean 3.92% / SD 1.73%
      3. 66 DTE: mean 2.79% / SD 1.09%
      4. 59 DTE; mean 2.75% / SD 1.20%
      5. 52 DTE: mean 2.33% / SD 0.88%
      6. 45 DTE: mean 2.23% / SD 0.87%
      7. 38 DTE: mean 1.88% / SD 0.75%
    (click to enlarge)


    Win Rate

    The win rate trends have been consistent across the DTEs tested:
    1. In general, win rates tend to increase as wing widths increase
    2. Win rates tend to decrease as the delta of the short strikes increases
      1. At 20 delta, there is only a slight increase in win rate when taking losses greater than 200%
    3. The 50% profit taking level has the highest win rates
    4. The top win rate was 99%, and was associated with four strategies:
      1. EL (NA:50), wing width 25, 8 delta
      2. ST (NA:50), wing width 75, 8 delta
      3. EL (NA:50), wing width 75, 8 delta
      4. DN (NA:50), wing width 75, 8 delta
    5. 82 strategies had win rates of 91% or better:
      1. Of these 82 , 57 took profits at 50%
      2. Of these 82 , 49 did not use loss exits (they exited at 2 DTE; loss taking % = NA)
      3. Of these 82 , 43 had short strike deltas of 8
      4. Of these 82 , 32 had wing widths of 75 points
    6. The strategies with the top win rates also had some of the largest single losses...and this is consistent across the DTEs tested
    (click to enlarge)


    Largest Loss

    The next charts show the normalized largest loss for each of the test runs  These largest losses are expressed as a percentage of the max risk found in the roughly 165 trades in each test run.

    The results:
    1. Typically, the largest loss percentage increases with increasing loss taking level
    2. There were three strategy variations that had losses measurably greater than 100% of risk.  They were the 25 point wing, 20 delta shorts, DN using a loss taking level of 300%.  These variations hit a loss of 126% of risk due to bad data.
      1. This bad quote was associated with the 17-Sep-2011 expiration, and occurred on 24-Aug-2011. This was the same expiration that was hit with bad data in other DTE trades.
    3. 36 strategy variations had largest loss readings of 95% or greater:
      1. Of these 36, 27 did not use a loss taking level (loss taking % = NA)
      2. Of these 36, 18 used wing widths of 25 points
      3. Of these 36, 18 used the DN structure
    4. 34 strategy variations had largest losses that were 29% or smaller:
      1. Of these 34, 32 used a loss taking level of 100%
      2. Of these 34, 23 had short strike deltas of 8
      3. Of these 34, 18 used the extra long put (EL) structure
      4. Of these 34, 18 used a profit taking level of 50%
      5. Of these 34, 16 used wing widths of 75 points
    5. The top three smallest losses were associated with the following strategies:
      1. EL (100:50), 75 point wings, 8 delta -> 16% loss  (win rate 80%)
      2. DN (100:50), 75 point wings, 8 delta -> 17% loss  (win rate 82%)
      3. DN (100:50), 50 point wings, 8 delta -> 18% loss  (win rate 82%)
    (click to enlarge)


    Profit Factor

    The profit factor results are listed below:
    1. Profit factors increase for variations not using a loss taking % (loss taking % = NA)
      1. This trend is most pronounced at the short strike delta of 8
    2. 216 strategy variations had profit factors of 2.0 or greater...this is a big increase again from the number of variations meeting this criteria lower DTE.
      1. 100 of these 216 took profits at 50%
      2. 85 of these 216 did not use a loss taking exit (loss taking % = NA)
      3. 82 of these 216 used the standard IC structure (ST) (73 used the DN structure)
      4. 78 of these 216 had short strike deltas of 8 (61 used 12 delta)
    3. The top tree performers were:
      1. DN (NA:50), 75 point wings, 12 delta -> profit factor of 3.1 (win rate 95%)
      2. DN (NA:50), 50 point wings, 8 delta -> profit factor of 3.0 (win rate 95%)
      3. EL (NA:50), 50 point wings, 8 delta -> profit factor of 3.0 (win rate 96%)
    (click to enlarge)


    Average DIT For Winning Trades

    This metric was derived by averaging all of the DIT for all of the winning trades in a test run. The trends associated with this metric are consistent with the prior DTE test runs:
    1. As short strike deltas increase, trade duration increases
    2. As profit taking level increases, trade duration increases
    3. The 50% profit taking level should have you out of your trade between 24 and 47 days for a 80 DTE IC, depending on short strike delta
    4. The smallest winning trade DIT of 24 was associated with 8 delta short strikes, 25 point wings, profit taking at 50%, loss taking at 100%, and the EL structure.  The same configuration but using either the ST or DN structures yielded a an average DIT for winning trades of 27
    5. There were 50 variations with winning trade DIT values less than 35:
      1. All 50 took profits at 50%
      2. 36 of these 50 used 8 delta short strikes
      3. 19 of these 50 used the loss taking level of 100%
    (click to enlarge)


    Follow my blog by email, RSS feed or Twitter (@DTRTrading).  All options are available on the top of the right hand navigation column under the headings "Subscribe To RSS Feed", "Follow By Email", and "Twitter". 

    Tuesday, March 21, 2017

    73 DTE Iron Condor Results Summary

    This article reviews the backtest results for iron condors (IC) entered at 73 days to expiration (DTE). These tests covered 9 IC variations, with short strike deltas at four locations (8, 12, 16, 20), utilizing 12 exits.  In all, there were 432 test runs (9 variations x 4 deltas x 12 exits). Each test run executed an average of 174 SPX IC trades between the January 2007 expiration and the September 2016 expiration.  A total of 432 ten year backtests.  I used weekly options for this testing, so there were more than 12 trades per year.  In total, there were 75,096 total trades entered for the 73 DTE testing.

    You can find the prior SPX IC posts in this series at the links below:

    Normalized P&L per Day

    The P&L per day values shown in the charts below are expressed as a percentage of the max risk for that test run.  Each of the different wing width ICs (25 point, 50 point, 75 point) will have a different max risk, and it is important to normalize daily returns by the associated max risk number.  For example, a 25 point IC will have slightly less than $25K max risk (margin), while a 75 point IC will have slightly less than $75K max risk (margin).  Since the 25 point IC will have approximately 1/3 the risk/margin, the $ returns need to be normalized by these varying max risk / margin numbers for proper strategy variation comparison.

    The results:
    1. We continue to see more variability in P&L per day readings in the 25 point wing ICs, than in the larger wing width ICs
    2. Similar to the prior test runs, as the delta of the short strikes increases, the variability in the P&L per day readings increases
    3. The largest reading was 0.17%, which is smaller than the largest reading for the 38, 45, and 59 DTE ICs.  There was one strategy variation with a 0.17% value:
      1. ST (100:75), 25 point wings, 20 delta
    4. The next best readings came in at 0.16% and were associated with four test runs: 
      1. ST (100:50), 25 point wings, 20 delta
      2. ST (NA:75), 25 point wings, 20 delta
      3. ST (300:75), 25 point wings, 20 delta
      4. ST (200:75), 25 point wings, 20 delta
    5. 46 strategy variations had P&L per day readings of 0.12% or greater:
      1. Of these 46, 35 used the standard balanced (ST) IC structure
      2. Of these 46, 30 used wing widths of 25 points
      3. Of these 46, 26 used the profit taking level of 50%
      4. Of these 46, 25 used a short strike delta of 20
    (click to enlarge)


    Normalized P&L per Trade

    The normalized P&L per trade charts display returns expressed as a percentage of the max risk for a given test run.  As trade duration increases with increasing DTE, overall P&L per trade increases. Due to this fact, the max value of the y-axis on the 73 DTE P&L per trade charts was increased from 6% to 12%.  The 16 delta and 20 delta variations had some values exceeding the 6% level.

    The results:
    1. The variability in normalized P&L per trade again increases as the delta of the short strike increases, and decreases with increasing wing width
    2. In general, the returns per trade increase with increasing loss taking %, and this trend continues to be more pronounced as the trades move out in time / DTE
    3. The largest normalized P&L per trade was 9.1% and was associated with two strategy variations:
      1. ST (NA:75), 25 point wings, 20 delta
      2. ST (300:75), 25 point wings, 20 delta
    4. 112 variations had P&L per trade values of 5.0% or greater...this is a huge number!:
      1. 60 of these 112 were standard (ST) structures (34 were DN structures)
      2. 57 of these 112 used a short strike delta of 20 (44 used 16 delta)
      3. 51 of these 112 did not use a profit taking level (44 used the 50% level)
      4. 44 of these 112 did not use a loss taking exit (41 used the 300% level)
      5. 44 of these 112 used 25 point wings (41 used 50 point wings)
    5. The 73 DTE ICs have the largest average P&L per trade readings:
      1. 73 DTE: mean 3.92% / SD 1.73%
      2. 66 DTE: mean 2.79% / SD 1.09%
      3. 59 DTE; mean 2.75% / SD 1.20%
      4. 52 DTE: mean 2.33% / SD 0.88%
      5. 45 DTE: mean 2.23% / SD 0.87%
      6. 38 DTE: mean 1.88% / SD 0.75%
    (click to enlarge)


    Win Rate

    The win rate trends have been consistent across the DTEs tested:
    1. In general, win rates tend to increase as wing widths increase
    2. Win rates tend to decrease as the delta of the short strikes increases
      1. As the short strike delta increases to 16 and 20 delta, there is only a slight increase in win rate when taking losses greater than 200%
    3. The 50% profit taking level has the highest win rates
    4. The top win rate was 96%, and was associated with four strategies:
      1. ST (NA:50), wing width 75, 8 delta
      2. EL (NA:50), wing width 75, 8 delta
      3. DN (NA:50), wing width 75, 8 delta
      4. EL (NA:50), wing width 50, 8 delta
    5. 49 strategies had win rates of 91% or better:
      1. Of these 49, 39 took profits at 50%
      2. Of these 49, 31 did not use loss exits (they exited at 2 DTE; loss taking % = NA)
      3. Of these 49, 26 had short strike deltas of 8
      4. Of these 49, 22 had wing widths of 75 points
    6. The strategies with the top win rates also had some of the largest single losses...and this is consistent across the DTEs tested
    (click to enlarge)


    Largest Loss

    The next charts show the normalized largest loss for each of the test runs  These largest losses are expressed as a percentage of the max risk found in the roughly 174 trades in each test run.

    The results:
    1. Typically, the largest loss percentage increases with increasing loss taking level
    2. There were three strategy variations that had losses measurably greater than 100% of risk.  They were the 25 point wing, 12 delta shorts, EL using a loss taking level of 300%.  These variations hit a loss of 117% of risk due to bad data.
      1. This bad quote was associated with the 17-Sep-2011 expiration, and occurred on 24-Aug-2011. This was the same expiration that was hit with bad data in the 66 DTE trades.
    3. 43 strategy variations had largest loss readings of 95% or greater:
      1. Of these 43, 27 used wing widths of 25 points
      2. Of these 43, 25 used the ST structure
      3. None of the 43 used a loss taking level (loss taking % = NA)
    4. 42 strategy variations had largest losses that were 29% or smaller:
      1. Of these 42, 33 had short strike deltas of 8 and loss taking at 100%
      2. Of these 42, 21 used wing widths of 75 points
      3. Of these 42, 19 used the extra long put (EL) structure
    5. The top three smallest losses were associated with the following strategies:
      1. DN (100:50), 75 point wings, 8 delta -> 15% loss  (win rate 82%)
      2. EL (100:75), 75 point wings, 8 delta -> 16% loss  (win rate 72%)
      3. ST (100:50), 75 point wings, 8 delta -> 17% loss  (win rate 77%)
    (click to enlarge)


    Profit Factor

    The profit factor results are listed below:
    1. Profit factors increase for variations not using a loss taking % (loss taking % = NA)
      1. This trend is more pronounced at the lower short strike deltas of 8 and 12
    2. 110 strategy variations had profit factors of 2.0 or greater...this is a big increase from the number of variations meeting this criteria at 66 DTE.
      1. 57 of these 110 did not use a loss taking exit (loss taking % = NA)
      2. 55 of these 110 used the delta neutral structure (DN)
      3. 49 of these 110 took profits at 50%
      4. 46 of these 110 had short strike deltas of 8
    3. The top tree performers were:
      1. DN (NA:50), 75 point wings, 12 delta -> profit factor of 3.1 (win rate 95%)
      2. DN (NA:50), 50 point wings, 8 delta -> profit factor of 3.0 (win rate 95%)
      3. EL (NA:50), 50 point wings, 8 delta -> profit factor of 3.0 (win rate 96%)
    (click to enlarge)


    Average DIT For Winning Trades

    This metric was derived by averaging all of the DIT for all of the winning trades in a test run. Adding a DIT exit to your profit and loss exits is worth considering.

    The trends associated with this metric are consistent with the prior DTE test runs:
    1. As short strike deltas increase, trade duration increases
    2. As profit taking level increases, trade duration increases
    3. The 50% profit taking level should have you out of your trade between 21 and 42 days for a 73 DTE IC, depending on short strike delta
    4. The smallest winning trade DIT of 21 was associated with 8 delta short strikes, 25 point wings, profit taking at 50%, loss taking at 100%, and the EL structure.  The same configuration but using either the ST or DN structures yielded a an average DIT for winning trades of 25
    5. There were 40 variations with winning trade DIT values less than 30:
      1. All 40 took profits at 50%
      2. 32 of these 40 used 8 delta short strikes
      3. 17 of these 40 used the loss taking level of 100%
    (click to enlarge)


    Follow my blog by email, RSS feed or Twitter (@DTRTrading).  All options are available on the top of the right hand navigation column under the headings "Subscribe To RSS Feed", "Follow By Email", and "Twitter".